A balance that doesn’t match the sales report
Ask a founder what the company sold last month and the answer comes quickly. Ask what the bank account will show on the 20th and there’s usually a pause. A young company can make good “sales” and still run short of cash. The two don’t always go hand in hand.
That pause is the reason digital banking for startups in India matters more than the dull name suggests. A five-person team can’t spare someone for a branch visit every time a signatory changes, or a weekend for matching statements to invoices. It needs to see its money, move it without fuss, and keep records as a by-product of normal work. This piece looks at where startups run into trouble with money, what online banking does about it, and where you should stay cautious.
Where startups struggle
Cash arrives late, bills arrive on time
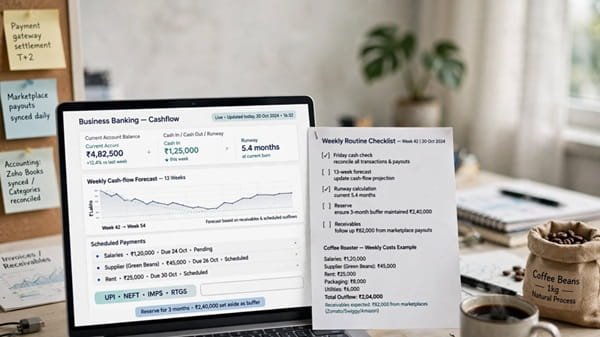
Now imagine a small coffee roaster that sells “coffee” on its website and through a big marketplace. The figures here are made up, just to show how cash flow works. It starts the month with ₹3.2 lakh. Salaries of “₹1.4 lakh” are due on the 1st, the bean supplier needs ₹2.1 lakh on the 3rd, and rent and utilities take another ₹45,000 on the 5th. There isn’t enough to cover all three payments. The business is short by ₹75,000, even though the marketplace owes it ₹2.6 lakh. That money won’t come through until the 12th.
Nothing is wrong with the company. It sold plenty. It was simply paid after it had to pay, and that gap between earning and receiving hits working capital whether or not the business is profitable.
Money lands in too many places
The same roaster collects through UPI, cards, a marketplace payout and the odd bank transfer from a café. Each shows up differently. The gateway settles a day or two late and deducts its fee first. The marketplace pays in one lump that covers hundreds of orders, minus commission and returns. A transfer from a café may carry only a reference code. Reconciling all this against orders is tedious at the best of times, and it gets much worse if you let a quarter pass without doing it.
The account that looked fine at opening
Banks have different rules for “MAB” (minimum account balances), transfer fees and daily limits. The time they take to resolve a complaint also varies. An account that works fine for a freelancer making a few payments each month may not be enough for a business that pays thirty vendors. Your needs in year two also won’t match the ones you had in month three, so it’s worth choosing with an eye on where you’ll be.
What digital banking changes about payments
The mechanics have improved a lot. NEFT and RTGS work day and night, IMPS transfers money in seconds, and many customers now use UPI to pay. Paying a supplier is no longer about writing a cheque and waiting for it to reach the right person.
There are limits, though. Caps on daily and per-transaction amounts differ between banks and between account types, and they change over time. Look at your own account’s terms before you rely on a transfer going through on a deadline.
Online payments also make it easier to keep track of money. You can check when a payment was made, how much was paid and who received it. Bank statements are available to download whenever you need them. Some business accounts also work with accounting software, which can save you from entering every payment by hand. Just check with your bank first, as this feature may not be available with every account or software.
When it does work, your job turns from typing figures into a sheet to checking what’s already there and fixing the odd mismatch.
Payments that repeat each month are the third gain. Salaries, subscriptions, rent and vendor bills can be scheduled or uploaded in bulk, so a payroll for ten people becomes one file and one approval. You can see on the “20th” which payments are due to go out on the 1st.
A cash-flow routine that fits a small team
Look weekly. Pick a fixed time, such as Friday afternoon, and spend a quarter of an hour on what came in, what went out and what’s due. Daily checks can make you jumpy, while monthly checks may reveal bad news too late.
Forecast about thirteen weeks ahead. A “basic spreadsheet” is enough. Add the money due to come in, the payments you need to make, and the balance left each week.
It will be wrong in places. Its use is to show you the week where things get tight while there’s still time to chase an invoice or delay a purchase.
Forecast clients as they behave. If a customer’s terms say 30 days and they’ve paid in 50 three times running, plan on 50. Also remember that Indian rules on delayed payments to micro and small suppliers exist, with a 45-day expectation in many cases. This may work in your favour as a supplier but against you as a buyer. Check the latest details with your “accountant”.
Keep a reserve apart from the main account. Every business has different needs, but many “founders” try to keep enough money aside for a few months of expenses. That way, a “late payment” won’t leave them scrambling for cash.
Work out runway monthly. Divide your cash by your net monthly burn. Do it once with the numbers you expect and again with a worse set. The distance between those two answers shows how much risk you’re carrying.
Tools worth setting up
A business current account is the foundation. Keep company money away from your personal account from the first day, and tax filing, bookkeeping and any future due-diligence request all become less painful.
Expense and accounting tools come next. They sort spending into categories and turn a long statement into something you can read, so you’ll see what the company spends on software, shipping or contractors. You’ll probably also find a subscription nobody has opened for months. You should check how the tool “charges” before you sign up — because per-user fees can add up quickly as your team grows.
For online sales, a payment gateway handles card, UPI and net-banking payments and transfers the money to your account. Check the fees, when you’ll receive the money and how refunds are dealt with. Some banks and gateways also have APIs for checking balances or making payments through your own software. Ask your bank if this works with your account and who can help if it stops working.
Security and compliance
Faster payments mean faster fraud, and small companies are easy to target because everyone is busy and habits are loose.
Phishing is the usual way in. An email or SMS imitates your bank, or a message that appears to come from a founder tells someone in finance to pay a “new” account today. Always call the person to verify a change in “bank details” before making the payment. When there are “shared logins” and “weak passwords”, it can make it easier for someone to take over an account. Give each person their own login and use multi-factor authentication. Also, don’t let one person handle both setting up and approving a payment.
Customer and financial data carry legal duties as well as practical ones. Store them carefully and share them only with those who need them. On compliance, understand your “KYC” requirements, “GST” and “TDS” obligations and any conditions tied to your account type. Rules change, so confirm with your bank and a chartered accountant. A blog post, this one included, shouldn’t be your only source.
Choosing the right service
Banks differ in their maintenance fees, MAB (minimum balance) rules and transfer charges. “Daily limits” matter too, especially if the business needs to send large payments, so it helps to know whether the bank can raise them. The account should also support the payment methods your customers and vendors usually use. If a transaction gets stuck, you’ll want to know how quickly the bank can sort it out and whether you can speak to a real person. “Accounting software” support, extra charges, staff logins, payment approvals and alerts are worth looking into as well. What works for a small team today may not be enough once the business grows or starts dealing with customers abroad.
After that, ask founders you know. A bank’s website tells you what the bank wants to say. Someone whose payment sat stuck for three days tells you the rest.
Mistakes to avoid
Personal and business expenses can be easy to mix up, but sorting them out at tax time can take weeks. A separate account for the business saves you that trouble and keeps its transactions in one place.
Overlooking fees and limits is another common one. Small charges add up, and a cap that surprises you on payroll morning ruins the day. Read the terms once, carefully.
Leave reconciliation for a quarter and a task that takes thirty minutes each week can eat up ten hours. Shared logins are another problem. When something goes “wrong”, it can be hard to tell who made the change. Choosing a bank because the app is pleasant says nothing about what happens when a payment fails. And planning only for the good case leaves you stuck the first time a client is late, which will happen.
Where this is heading
Digital payments in India are still developing, and I expect more of the same over the next few years: tools that read your transactions and flag odd spending, forecasts built from your own history, and money features tucked inside software you already use. The last of these is called embedded finance, and it may mean you get payments or credit without opening a bank’s own site.
Some of this will help and some will be marketing. Try it with a few transactions first. Any tool that analyses your payments can access sensitive information, so it’s worth knowing where that data is kept and who has access before linking it to your bank account.
To follow the funding and fintech stories behind these changes, Malik Times covers startup and business news worth keeping an eye on. https://maliktimes.in/
A reasonable place to start
Digital banking won’t fix poor money habits, but it makes good ones easier to keep. It shows you your cash clearly, moves it quickly, and cuts the typing out of record-keeping, which matters when the team is small and everyone has three jobs.
Pick tools that suit your size, your budget and how the company works today, and look again when things change. If you do three things this week, separate your accounts if they’re still mixed, block fifteen minutes on Friday for a cash check, and sketch a thirteen-week forecast. The first forecast will teach you more than this article did.