Top 10 Pharmacy Chains in India 2026 reveal a market shaped almost entirely by conglomerate acquisitions — Reliance Industries bought Netmeds in 2020, Tata Digital acquired a majority stake in 1mg in 2021 for roughly $325-350 million, and Apollo HealthCo’s combined digital and offline pharmacy business alone reported Q1 FY27 revenue of ₹2,977 crore, up 20 percent year-on-year. India’s ₹30,122 million pharmacy retail market is growing at a 9.80 percent CAGR toward a projected $52.8 billion by 2031, yet organised chains still capture only a fraction of a sector where independent neighbourhood pharmacies remain deeply entrenched. This list covers the top 10 pharmacy chains in India in 2026.
| Rank | Chain | Founded | Stores/Scale |
| 1 | Apollo Pharmacy | 1983 | India’s largest, omni-channel leader |
| 2 | MedPlus | 2006 | 5,500+ stores, 800+ cities |
| 3 | Wellness Forever | — | $1.1B revenue |
| 4 | Tata 1mg | 2015 | Digital + physical network |
| 5 | PharmEasy | 2015 | ₹5,872 crore revenue |
| 6 | Netmeds | — | Reliance Retail-owned |
| 7 | Amazon Pharmacy | — | E-commerce entrant |
| 8 | Guardian Pharmacy | — | Established retail chain |
| 9 | Frank Ross Pharmacy | — | Legacy retail chain |
| 10 | Zeelab Pharmacy | — | Digital-forward chain |
1. Apollo Pharmacy
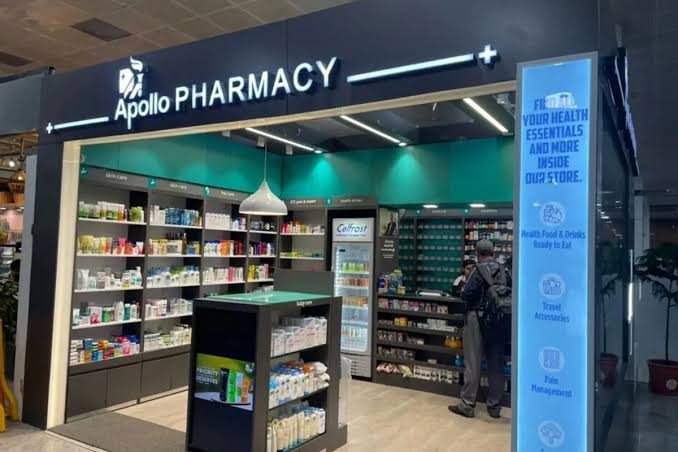
Apollo Pharmacy, founded in 1983, stands as India’s largest and most established pharmacy chain, now operating through an integrated omni-channel healthcare retail model under Apollo HealthCo.
- Reported Q1 FY27 revenue of ₹2,977 crore, up 20 percent year-on-year, with segment EBITDA of ₹171 crore
- Offline pharmacy distribution alone generated ₹2,335 crore in a recent quarter, alongside ₹326 crore from digital platform revenue
- Apollo 24|7’s digital GMV reached ₹723 crore, up 16 percent year-on-year
- Backed by the broader Apollo Hospitals Group’s decades of healthcare credibility and infrastructure
2. MedPlus Health Services
MedPlus stands as India’s second-largest pharmacy chain by both store count and revenue, founded by Madhukar Gangadi in 2006 and headquartered in Hyderabad.
- Operates over 5,500 pharmacy stores across more than 800 cities as of 2026
- Reported FY23 revenue of ₹4,603 crore with net income of ₹49 crore
- Runs additional subsidiaries including MedPlusMart.com, MedPlusLab.com, and MedPlusLens.com
- Demonstrates superior scale and pricing power compared to smaller regional pharmacy chains
3. Wellness Forever
Wellness Forever has emerged as India’s highest-revenue pharmacy company, according to recent industry rankings, standing ahead of even the digital-first giants in overall revenue terms.
- Ranked first among India’s drug store and pharmacy companies by revenue, with $1.1 billion reported
- Represents one of India’s significant physical retail pharmacy chains competing directly with Apollo and MedPlus
- Continues to be cited among the major companies operating within India’s organised pharmacy retail market
- Demonstrates that traditional retail-focused pharmacy chains can outpace even well-funded digital platforms on pure revenue
4. Tata 1mg
Tata 1mg, founded in 2015 by Prashant Tandon, Gaurav Agarwal, and Vikas Chauhan, has built an integrated digital healthcare platform now backed by Tata Digital’s majority ownership.
- Reported consolidated turnover of ₹2,392 crore in FY2025 for its India operations
- Tata Digital acquired approximately 55 percent stake in the company, reportedly valued between $325-350 million
- Offers integrated e-pharmacy, e-diagnostics, and tele-consultation services alongside a growing physical retail and lab network
- Has expanded into speciality care including cancer care, obesity management, and at-home adult vaccination services
5. PharmEasy
PharmEasy, founded in 2015 by Dharmil Sheth and Dhaval Shah, operates as one of India’s most prominent e-pharmacy platforms despite ongoing profitability challenges.
- Generated operating revenue of ₹5,872 crore in FY2025, among the highest in the sector
- Continued reporting substantial losses despite scale, illustrating the sector’s genuine discounting and profitability pressure
- Serves over 1,000 cities across India through its medicine delivery and healthcare services platform
- Withdrew its planned IPO in August 2022, reflecting the broader financial challenges facing venture-funded e-pharmacy platforms
6. Netmeds
Netmeds operates as part of Reliance Retail’s broader JioMart ecosystem, following Reliance Industries’ acquisition of the platform in 2020.
- Fully integrated into Reliance Retail’s JioMart digital commerce ecosystem
- Benefits from Reliance’s extensive logistics, distribution, and customer acquisition infrastructure
- Regularly ranks among India’s top five most-visited pharmacy websites
- Represents one of the clearest examples of conglomerate-backed consolidation reshaping India’s pharmacy retail landscape
7. Amazon Pharmacy
Amazon Pharmacy represents the global e-commerce giant’s entry into India’s organised pharmacy retail category, competing directly with homegrown digital platforms.
- Entered India’s pharmacy category leveraging Amazon’s existing logistics and customer base infrastructure
- Competes directly with PharmEasy, Tata 1mg, and Netmeds for India’s growing online medicine delivery market
- Benefits from Amazon’s broader e-commerce trust and delivery reliability reputation
- Represents the continued internationalisation of India’s competitive digital pharmacy landscape
8. Guardian Pharmacy
Guardian Pharmacy has established itself as a well-recognised physical retail pharmacy chain across major Indian cities.
- Operates as a significant brick-and-mortar pharmacy retail presence within India’s organised segment
- Competes alongside Apollo Pharmacy and MedPlus in physical retail pharmacy distribution
- Represents the traditional retail pharmacy model within an increasingly digital-first competitive landscape
- Continues serving customers who prioritise in-person pharmacy consultation and immediate medicine access
9. Frank Ross Pharmacy
Frank Ross Pharmacy carries genuine legacy status among India’s organised pharmacy retail chains, with decades of established brand presence.
- Represents one of India’s longer-standing physical pharmacy retail chains
- Maintains presence across multiple major Indian cities through its retail store network
- Competes within the traditional brick-and-mortar segment alongside Guardian Pharmacy and regional players
- Continues serving customers within India’s substantial, still largely unorganised broader pharmacy retail market
10. Zeelab Pharmacy
Zeelab Pharmacy rounds out this list as a digital-forward pharmacy chain gaining visibility within India’s competitive online medicine retail space.
- Regularly featured among India’s top five most-visited pharmacy websites
- Competes directly with PharmEasy, Netmeds, and Tata 1mg for online medicine delivery customers
- Represents the continued fragmentation and competition within India’s digital pharmacy retail segment
- Contributes to the broader growth of organised, technology-enabled pharmacy access across the country
Frequently Asked Questions
Q1. Which is India’s largest pharmacy chain in 2026?
Apollo Pharmacy holds that position, backed by its omni-channel model combining offline distribution and digital platform revenue, with MedPlus following as the second-largest by store count and revenue.
Q2. Why have so many Indian pharmacy chains been acquired by large conglomerates?
Reliance Industries, Tata Digital, and Amazon have all entered pharmacy retail through acquisitions or direct investment, recognising the sector’s long-term growth potential despite the significant capital and logistics investment required to scale profitably.
Q3. Is PharmEasy’s high revenue a sign of a genuinely profitable business?
Not necessarily — despite generating ₹5,872 crore in operating revenue, PharmEasy has continued reporting substantial losses, illustrating that scale alone doesn’t guarantee sustainable pharmacy retail economics.
Q4. Should I choose an online pharmacy or a physical pharmacy chain for regular medicine purchases?
It depends on your priorities — digital platforms like Tata 1mg and PharmEasy offer convenience and often better pricing, while physical chains like Apollo Pharmacy and Guardian Pharmacy provide immediate access and in-person pharmacist consultation.