Top 10 Hospital Chains in India 2026 are led by Apollo Hospitals, which operates over 10,209 beds across 73-plus facilities and now holds a market capitalisation exceeding ₹1,26,000 crore — yet the more profitable story sits with Max Healthcare, which delivers the sector’s highest average revenue per occupied bed at ₹2.84 crore despite operating a considerably smaller network. India’s hospital sector is now valued above ₹8 lakh crore, with Jefferies projecting a capacity-led growth phase through 2026-28 as major chains collectively add thousands of new beds to meet rising healthcare demand. This list covers the top 10 hospital chains in India in 2026.
| Rank | Chain | Market Cap (₹ Cr) | Bed Capacity |
| 1 | Apollo Hospitals | 1,26,786+ | 10,209 beds |
| 2 | Max Healthcare | 98,656 | 5,000+ beds |
| 3 | Fortis Healthcare | 69,154 | 5,554-5,800 beds |
| 4 | Narayana Hrudayalaya | 36,837 | 6,100 beds |
| 5 | Aster DM Healthcare | 32,444 | 5,000 beds |
| 6 | Global Health (Medanta) | 15,000+ | Expanding capacity |
| 7 | KIMS (Krishna Institute) | — | 4,900 beds |
| 8 | Manipal Hospitals | Private | Large pan-India network |
| 9 | Shalby Hospitals | — | 2,062 beds |
| 10 | HCG (HealthCare Global) | — | Oncology-focused network |
1. Apollo Hospitals
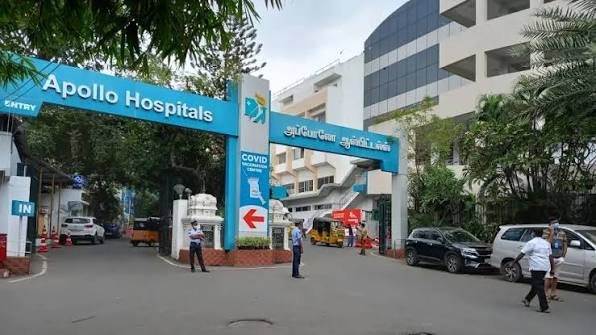
Apollo Hospitals stands as India’s largest and most diversified hospital chain, combining hospital operations with pharmacy retail and digital health services under one integrated ecosystem.
- Operates over 10,209 beds across 73 hospitals, the largest bed capacity of any Indian hospital chain
- Holds a market capitalisation of ₹1,26,786 crore, the largest among all listed hospital stocks
- Delivers the strongest Return on Equity in the sector at 20.48 percent, driven partly by its diversified pharmacy and telemedicine businesses
- Planning to add more than 1,000 additional beds over the next 12-18 months as part of its continued expansion
2. Max Healthcare
Max Healthcare has built the most operationally efficient hospital network in India, generating the highest average revenue per occupied bed in the entire sector.
- Delivers an ARPOB of ₹2.84 crore per bed, the highest among major Indian hospital chains
- Reported FY25 revenue of approximately ₹7,028-7,000 crore with an EBITDA margin of 20-22 percent, among the strongest in the sector
- Operates 20 hospitals with 3,454-5,000 beds, concentrated primarily in premium metro markets
- Jefferies has named it a top pick, projecting 22 percent EBITDA CAGR over FY26-28 alongside plans to add over 3,000 beds by 2028
3. Fortis Healthcare
Fortis Healthcare represents one of India’s most notable hospital sector turnaround stories, having recovered significantly following past ownership challenges under IHH.
- Market capitalisation of ₹69,154 crore, with FY25 revenue of ₹7,783 crore
- Operates between 4,600-5,800 beds depending on the specific reporting period
- Delivers a Return on Equity of 10.53 percent, the lowest among major listed peers, reflecting its ongoing operational recovery phase
- Jefferies projects 18 percent EBITDA CAGR through FY26-28, with plans to add around 700 beds over 12-18 months
4. Narayana Hrudayalaya
Narayana Hrudayalaya has built its distinctive reputation around affordable, high-volume healthcare delivery, proving profitability doesn’t require premium pricing.
- Operates 6,100 beds, the second-largest bed capacity among India’s hospital chains
- Reported FY25 revenue of ₹5,483 crore with a Return on Equity of 17.76 percent
- Delivers a lower ARPOB of ₹1.75 crore per bed, reflecting its deliberate focus on affordable, accessible care
- Trades at the most value-oriented valuation among major hospital stocks, with a PE ratio of 45-47
5. Aster DM Healthcare
Aster DM Healthcare rounds out India’s top five listed hospital chains by market capitalisation, maintaining a substantial bed network across multiple regions.
- Market capitalisation of ₹32,444 crore
- Operates approximately 5,000 beds, placing it among the top four Indian hospital chains by capacity
- Maintains significant presence extending beyond India into Gulf markets, reflecting a genuinely international healthcare footprint
- Continues to be tracked among the top five hospital companies by both market cap and bed capacity
6. Global Health (Medanta)
Global Health, operating under the Medanta brand, has built a reputation for premium, technologically advanced tertiary care across its hospital network.
- Market capitalisation exceeding ₹15,000 crore
- Recently completed a 300-bed expansion at its Noida facility
- Known for advanced specialised treatment capabilities across cardiac, neurology, and complex surgical care
- Represents one of India’s most recognised premium tertiary care hospital brands
7. KIMS (Krishna Institute of Medical Sciences)
KIMS has built a strong regional hospital network, particularly concentrated across South India’s healthcare market.
- Operates approximately 4,900 beds, placing it among India’s top five hospital chains by capacity
- Maintains strong presence across Telangana, Andhra Pradesh, and neighbouring South Indian states
- Represents one of the fastest-growing regional hospital networks in the country
- Continues expanding its multi-speciality tertiary care capabilities across its operating regions
8. Manipal Hospitals
Manipal Hospitals operates as one of India’s largest privately held hospital networks, though it remains unlisted unlike most of its major competitors.
- Maintains a substantial pan-India hospital network spanning multiple states and cities
- Backed by the broader Manipal Group’s decades of healthcare and education sector expertise
- Recently expanded through significant acquisitions, growing its overall bed capacity and geographic reach
- Represents one of the largest hospital chains operating outside the public listed markets
9. Shalby Hospitals
Shalby Hospitals has built a focused, efficient hospital network particularly known for orthopaedic and joint replacement specialisation.
- Operates 2,062 beds across its hospital network
- Particularly recognised for its expertise in orthopaedic surgery and joint replacement procedures
- Represents a more specialised positioning compared to the broader multi-speciality chains dominating this list
- Continues to be tracked among India’s significant mid-sized listed hospital chains
10. HCG (HealthCare Global Enterprises)
HCG rounds out this list as India’s leading dedicated oncology-focused hospital chain, addressing a specific and growing healthcare need.
- Specialises specifically in cancer care and oncology treatment across its hospital network
- Represents a distinctly specialised positioning compared to the multi-speciality chains elsewhere on this list
- Benefits from India’s rising cancer treatment demand and increasing health insurance coverage for oncology care
- Continues expanding its dedicated cancer care network across multiple Indian cities
Frequently Asked Questions
Q1. Which hospital chain has the largest bed capacity in India?
Apollo Hospitals leads with over 10,209 beds across 73 hospitals, well ahead of Narayana Hrudayalaya’s 6,100 beds and Max Healthcare’s roughly 5,000 beds.
Q2. Which hospital chain is considered the most operationally efficient?
Max Healthcare delivers the highest average revenue per occupied bed at ₹2.84 crore, alongside the strongest EBITDA margins in the sector at 20-22 percent.
Q3. Is a larger hospital chain always a better investment than a smaller, specialised one?
Not necessarily — specialised chains like Shalby (orthopaedics) or HCG (oncology) can deliver strong returns within their niche, while larger diversified chains like Apollo benefit from broader scale and cross-selling through pharmacy and diagnostics.
Q4. Why does Narayana Hrudayalaya generate lower revenue per bed than Apollo or Max Healthcare?
Narayana Hrudayalaya deliberately focuses on affordable, high-volume healthcare delivery rather than premium pricing, which results in a lower ARPOB despite still delivering strong overall profitability.